 7132 178 St NW,

 Call us:

 Call us780-809-1056
- Mail usinfo@inspecus.ca
- Schedule An Inspection
Call us780-809-1056

Meta description: Can a home inspection lower your Edmonton insurance premium? Learn what insurers review, 2026 costs, WETT reports, roof age, wiring and water-risk documentation.
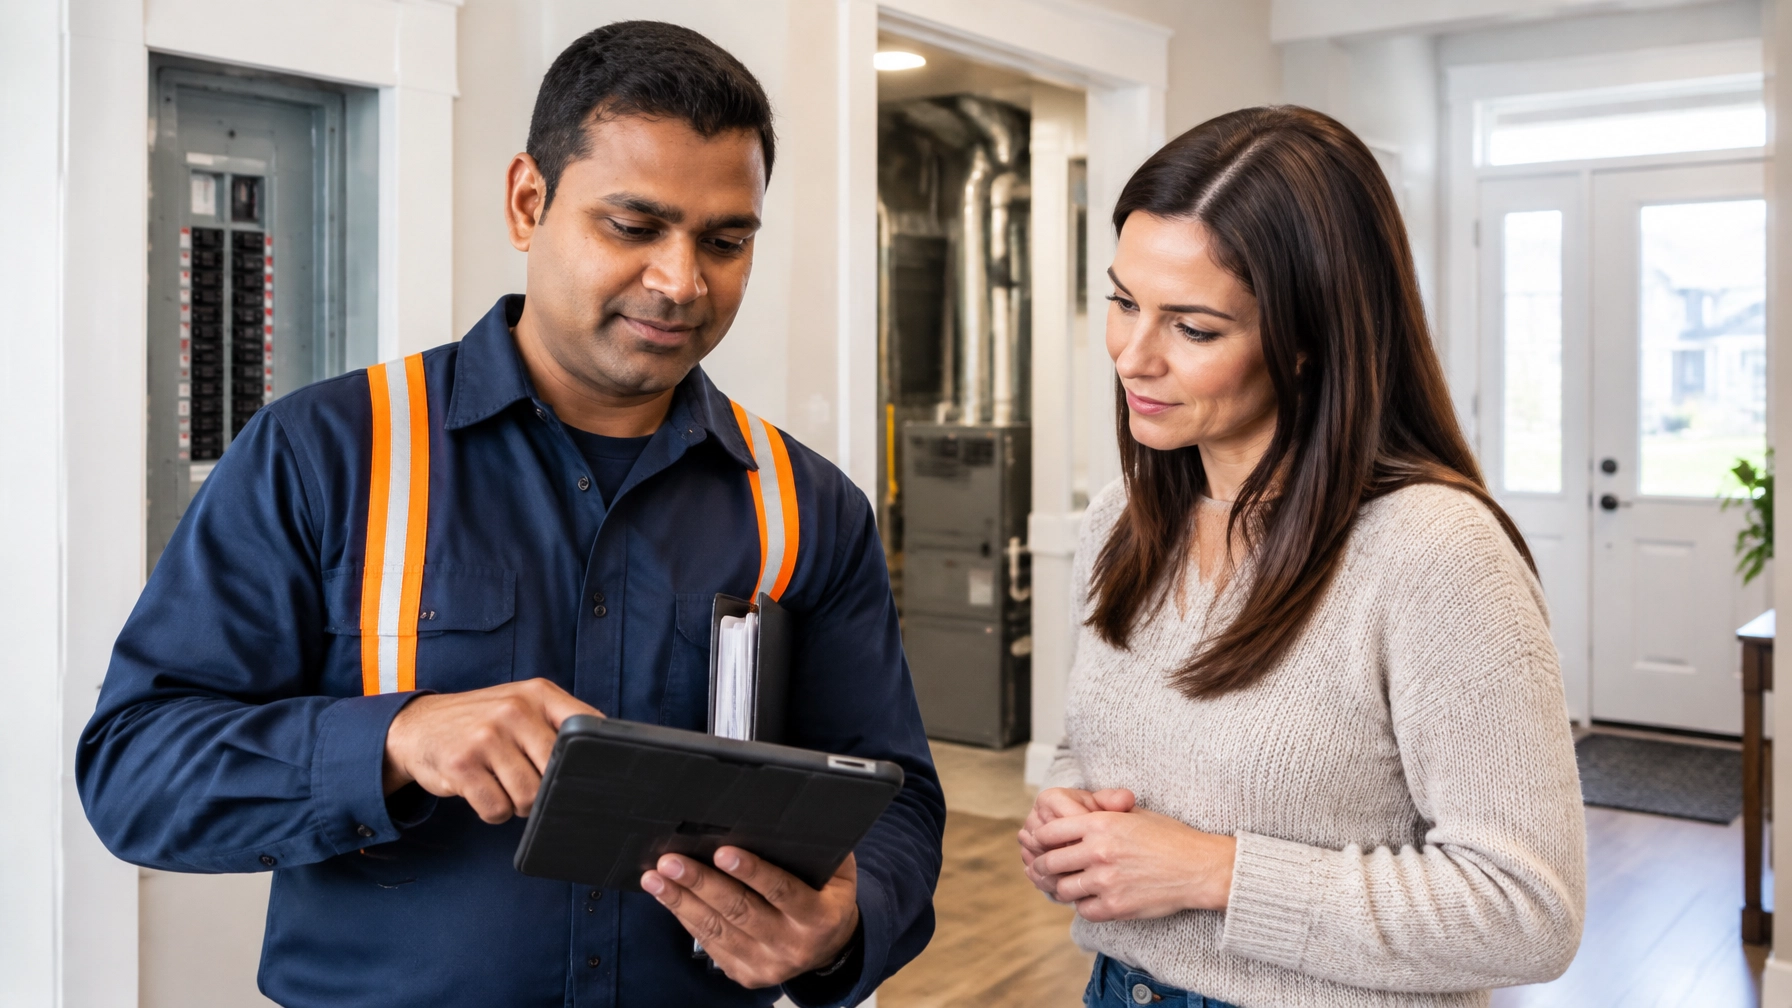
Direct answer: A standard home inspection does not automatically lower your Edmonton insurance premium. However, it can document the age and condition of risk-sensitive systems, such as the roof, wiring, plumbing, heating, foundation, and drainage. Corrected issues, specialist reports, and repair records may help you qualify for coverage or insurer-specific savings.
When you search for a home inspection in Edmonton, cost is usually your first question. The next question is often more practical: Will the inspection help me save money after I buy?
The honest answer is that a home inspection is not an automatic insurance discount. Insurers do not generally reduce your premium simply because you ordered a buyer’s inspection.
However, a thorough report can reveal and document the property characteristics that insurers actually consider when assessing risk. If you correct those issues and provide evidence to your broker, the inspection may help you secure better coverage terms, avoid exclusions, or qualify for insurer-specific credits.
I’m Banti K Shaw, owner of InspecUs. With more than 10 years of construction experience and more than 10 years inspecting homes and properties, I understand how building conditions affect both your purchase decision and your long-term ownership costs.
“An inspection does not promise an insurance discount. What it gives you is reliable information. That information can help you correct risks, compare policies, and avoid expensive surprises.”
Banti K Shaw, Owner, InspecUs
Could the report lower your premium directly? Usually, no.
A standard inspection is designed to provide an unbiased assessment of accessible building systems. It is not an insurance rating inspection, warranty, engineering assessment, or guarantee of future performance.
Insurers set premiums using their own underwriting rules. According to the Insurance Bureau of Canada’s explanation of home insurance rates, common factors include:
Your inspection report can support this conversation, particularly when it contains clear photos, equipment information, and descriptions of visible conditions.
For example, an insurer may ask whether the home has knob-and-tube wiring, aluminum branch wiring, an older roof, galvanized plumbing, a wood stove, a secondary suite, or evidence of previous water damage. Your report may help you answer those questions accurately.
Which findings matter most to an Edmonton insurer? Focus on systems connected to fire, water, weather, and liability risk.
Edmonton homes face hail, high winds, snow loading, ice dams, and repeated freeze-thaw cycles. Insurers may ask for:
An old roof does not automatically make a home uninsurable. However, an insurer may limit coverage, require repairs, apply a higher deductible, or ask for a roof inspection depending on its condition and underwriting rules.
Older Edmonton neighbourhoods, including homes built before the 1960s, may contain electrical systems that require closer review. Insurers commonly ask about:
A home inspector can report visible wiring types and panel information, but suspected hazards should be evaluated by a qualified electrician. Your insurer may require a separate electrical safety letter or documentation of completed remediation.
Water claims are a major concern for property insurers. A report may identify:
The inspection does not determine every concealed pipe material or guarantee that a hidden leak does not exist. It provides an informed visual record of accessible components on the inspection date.
Heating equipment affects fire, carbon monoxide, and winter habitability risks. A report may document:
If you are buying an older Edmonton or Saint Albert property, you can also review our guide on furnace concerns before purchasing a Saint Albert home.
Do you need a WETT inspection for a wood stove? Often, yes.
A standard home inspection may identify the presence and visible condition of a fireplace or wood stove, but it does not replace a specialist WETT inspection. Many insurers request WETT documentation before binding or renewing coverage for a wood-burning appliance.
A WETT inspection may review:
Requirements vary by insurer, so ask your broker what type and age of report they require. InspecUs also provides WETT and chimney inspection services in Edmonton.
Can grading affect insurance? It can affect your property’s water risk, even though an inspection cannot change the home’s location or flood map.
An inspector may document:
In Edmonton, sewer-backup coverage and overland-flood coverage are often separate policy considerations. The Government of Alberta’s property insurance information recommends speaking directly with your insurer about available coverage, limits, exclusions, and deductibles.
An inspection can document visible mitigation features, but it cannot confirm that your policy includes sewer backup or overland flooding. Always ask your broker directly.

What should you send your broker after the inspection? Do not simply email a large report without context. Make the insurer’s review easier.
Use this process:
Ask what documents are required.
Confirm whether your broker needs the full report, a roof document, an electrical inspection, a WETT report, or another insurer-specific form.
Highlight the relevant pages.
Point out the roof age, electrical service, wiring type, plumbing materials, furnace information, wood-burning appliances, drainage features, and secondary suite observations.
Attach proof of completed work.
Include paid invoices, permits where applicable, electrician letters, roof warranties, WETT documents, and before-and-after photographs.
Ask specific questions.
For example:
Compare more than one quote.
Insurers do not all treat the same property feature the same way. A broker can explain which improvements affect eligibility, coverage, or pricing with each carrier.
“I always encourage buyers to give the broker facts, not assumptions. A report may identify a risk, but the insurer decides how that risk affects coverage.”
Banti K Shaw, Owner, InspecUs
Can thermal imaging improve insurance documentation? It can provide useful supporting evidence when there is a specific concern.
Thermal imaging may help identify unusual temperature patterns around:
A thermal image is not proof of a leak by itself. Findings should be confirmed with appropriate testing, including a moisture meter or specialist assessment where necessary.
Consider adding thermal imaging and moisture detection when:

What should you budget for a home inspection in Edmonton? There is no single reliable price for every property.
The cost depends on:
A lower inspection fee may not be the best value if the report lacks clear photographs, system details, or practical explanations. InspecUs examines more than 100 items, uses advanced tools, and delivers same-day reports or reports within 24 hours with high-resolution images.
For a property-specific quote, visit our pre-purchase home inspection service in Edmonton.
Can an inspection guarantee insurance approval or future savings? No.
A home inspection:
The InterNACHI Standards of Practice describe a home inspection as a non-invasive visual examination of accessible areas and specifically note that it does not determine insurability.
For a broader explanation of what is inspected, read our 100-point Edmonton home inspection checklist.
A home inspection may pay for itself by helping you identify a major repair before closing, negotiate with better information, avoid unsuitable coverage, or document upgrades for your broker.
But it would be misleading to promise that the inspection itself will lower your premium.
At InspecUs, I provide unbiased reporting without third-party influence. With InterNACHI certification, more than 10 years of construction and inspection experience, 250+ positive Google reviews, high-resolution photographs, and continued support after the inspection, my goal is simple: help you understand the property before you commit.
If you are buying an Edmonton-area home, the next step is to request a pre-purchase inspection quote.
We are licensed by the Licensed Professional and certified through InterNACHI

InspecUs Home Inspection is certified in the best practices established by Internachi. Our commitment to safety includes maintaining a 6-foot distance and using personal protective equipment (PPE) during all inspections.

© 2024 InspecUs - All Rights Reserved. | Sitemap | Developed by Integrated Marketing Platform Inc.